
Business Insurance Done Right.
Supporting our clients with structured personal coverage that aligns with their overall risk.
General Liability
Protects you from everyday business risks
General Liability covers third-party claims like bodily injury, property damage, and advertising injury. It’s the foundation of most business insurance policies and often required by landlords, clients, or vendors.
Typical examples:
- A customer slips and falls at your location
- Property damage caused by your operations
- Claims related to advertising or marketing materials
Best for:
Most businesses, regardless of size or industry.
Professional Liability (E&O)
Professional Liability covers claims that your services, advice, or work caused financial loss
General Liability covers third-party claims like bodily injury, property damage, and advertising injury. It’s the foundation of most business insurance policies and often required by landlords, clients, or vendors.
Typical examples:
- Client claims negligence or error
- Missed deadlines or incorrect advice
- Failure to perform services as expected
Best for:
Consultants, agencies, professionals, and service-based businesses.
Business Owner’s Policy (BOP)
Bundled coverage that simplifies protection and lowers cost.
A BOP combines General Liability and Commercial Property into one streamlined policy, often at a lower premium than purchasing separately.
Typically includes:
- General Liability
- Property coverage
- Business interruption (in many cases)
Best for:
Small to mid-sized businesses with a physical location or assets.
Workers’ Compensation
Required coverage for employee injuries and illnesses.
Workers’ Comp provides medical benefits and wage replacement for employees injured on the job. Requirements vary by state, industry, and number of employees.
Covers:
- Medical expenses
- Lost wages
- Employer liability protection
Best for:
Businesses with employees
Commercial Auto Insurance
Coverage for vehicles used for business purposes.
Commercial Auto covers vehicles owned, leased, or used for business operations. Personal auto policies usually exclude business use.
Covers:
- Liability for accidents
- Vehicle damage
- Hired & non-owned auto (when applicable)
Best for:
Contractors, delivery services, service businesses, fleets.
Commercial Property Insurance
Protection for your physical business assets.
Commercial Property covers buildings, equipment, inventory, furniture, and other business property against covered losses like fire, theft, or vandalism.
Can include:
- Building coverage
- Business personal property
- Loss of income after a covered event
Best for:
Businesses with locations, inventory, or valuable equipment.
Inland Marine Insurance
Coverage for property that moves or travels.
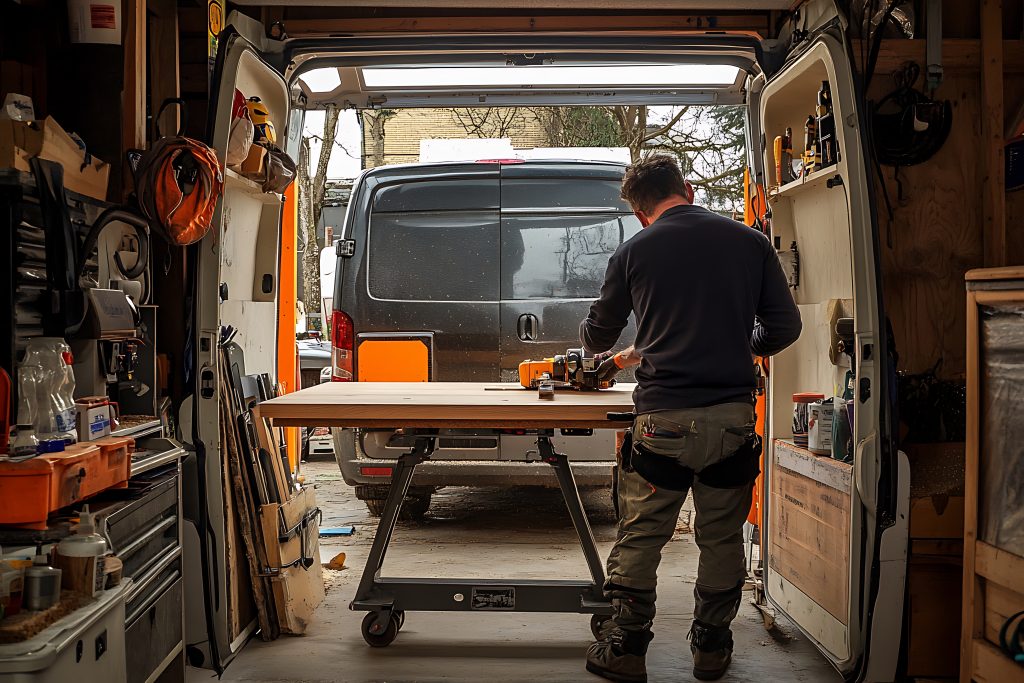
Inland Marine covers tools, equipment, and property while in transit or temporarily offsite—things traditional property policies may exclude.
Common uses:
- Contractor tools
- Mobile equipment
- Equipment used at job sites
Best for:
Contractors, trades, and mobile businesses.
Cyber Liability Insurance
Protection against data breaches and cyber incidents
Cyber coverage helps businesses respond to data breaches, ransomware, and cyber attacks—covering both first-party costs and liability to others.
May cover:
- Data breach response
- Notification and credit monitoring
- Ransomware and cyber extortion
Best for:
Any business handling customer data, payments, or sensitive information.
Surety Bonds
Financial guarantees required for certain jobs or licenses.
Bonds aren’t insurance in the traditional sense—they guarantee performance, compliance, or payment as required by contracts or regulators.
Common bond types:
- License & permit bonds
- Contractor bonds
- Performance & payment bonds
Best for:
Contractors, licensed professionals, and regulated industries.
Umbrella & Excess Liability
Extra protection above standard policy limits.
Umbrella insurance provides additional liability limits once underlying policies (GL, Auto, WC) are exhausted.
Best for:
Businesses with higher risk exposure or larger contracts.
Not sure what you actually need?
That’s normal. We’ll walk through your business, explain your options clearly, and help you avoid unnecessary coverage.